

Say what you want about President Donald Trump, but his top Lieutenant, Treasury Secretary Scott Bessent, is no fool. New York hedge fund don and Ivy League professor of economic history, Secretary Bessent is acutely aware of America’s responsibility as the backbone of the global banking system and the importance of the Treasury therein. He has the industry chops and the political acumen for a role that will grow in importance as the world reckons with unsustainable debt levels, rising interest rates, and the unpredictable fallout that will inevitably follow. That is why last week’s intervention is so noteworthy, even if you’re Canadian.
Yankee See
The yen’s recent slide is becoming a problem. This is because in a world of interconnected capital markets, global risk is synchronized. A blow-up in one of the world’s biggest economies could quickly destabilize global markets. Think the collapse in the U.S. mortgage-backed securities and the GFC. An uncontrolled collapse of the Japanese yen would have similar repercussions.
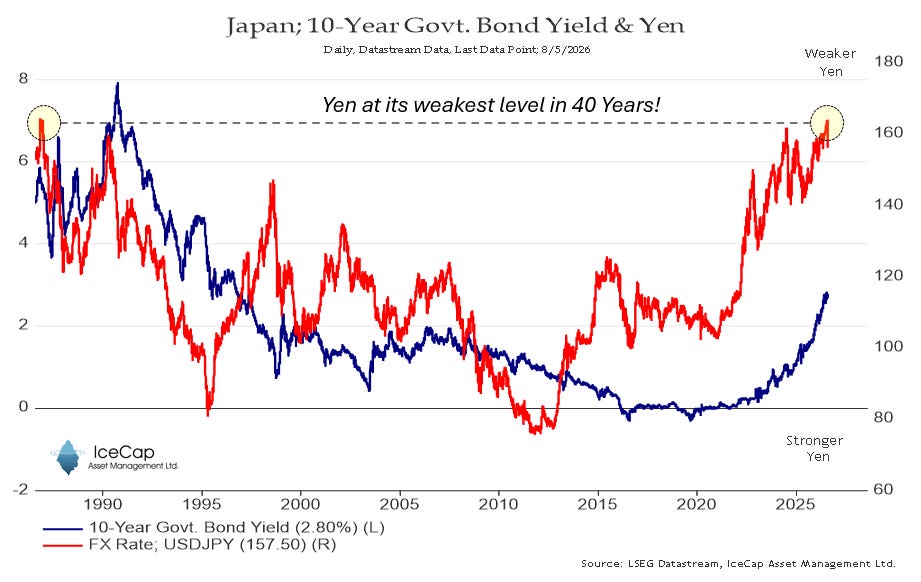
At nearly 164 yen to the dollar, the calculus for Secretary Bessent and the BOJ was straightforward. Intervene or risk a collapsing yen and destabilizing regional currencies and global capital markets.
Yankee Do
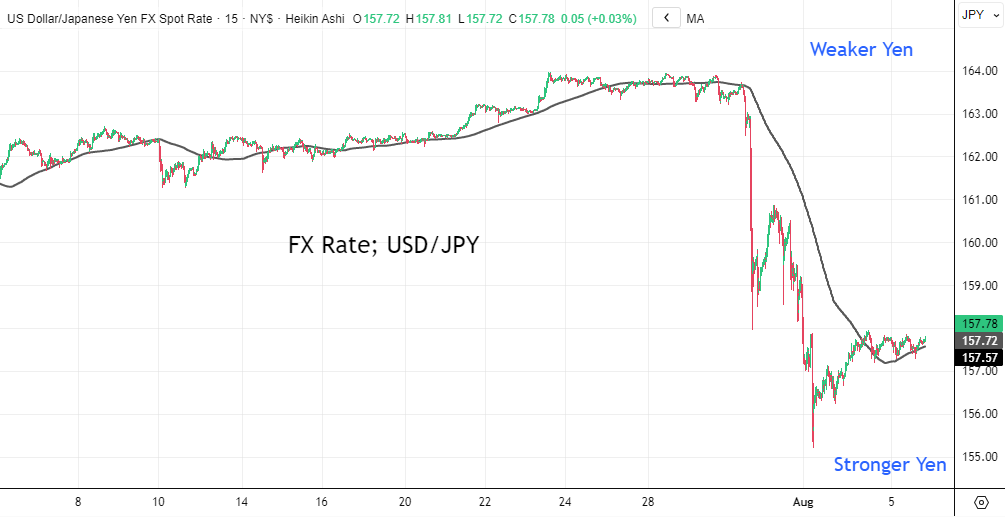
The mechanics of the intervention were carefully engineered and revealing. Japanese authorities moved first, buying yen on a scale estimated in the tens of billions. The U.S. joined in on July 31st, acting on behalf of the Treasury; the Federal Reserve Bank of New York sold euros from U.S. reserves to purchase yen. The result was that the USD/JPY fell from 164 to 158 and then to 156. It has stabilized at 157, for now, but more on that in a minute.
The decision to sell euros rather than dollars was deliberate: selling dollars directly would have carried its own unwelcome signal about U.S. fiscal and monetary policy. Japan holds roughly $1.2 trillion in U.S. Treasuries (~13% of foreign holdings), and large-scale Japanese sales of those holdings to fund yen purchases would have pushed U.S. yields higher at precisely the moment longer-term borrowing costs were already rising. By selling euros instead, and by encouraging Japan to use the Fed’s FIMA Repo Facility — which allows foreign central banks to borrow dollars against Treasuries rather than selling them outright — the U.S. helped contain the collateral damage to its own bond market.
The intervention became public in an unlikely way. A Reuters photograph taken during a cabinet meeting at Camp David captured Secretary Bessent’s notepad, on which was written: “Buy Japanese Yen (JPY) $5-10 bil.” Bessent later confirmed the action, stating the U.S. would “do whatever it takes” to support further joint efforts if needed.
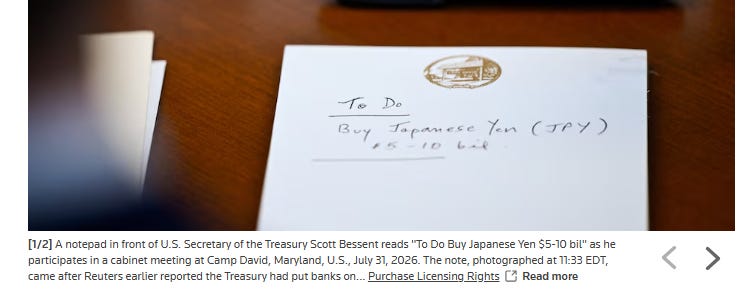
Sharing the notepad was pure theatre, but the intervention was not. It was the first time the U.S. and Japan had jointly bought yen in nearly thirty years. The last comparable action was in 1998. That alone should tell you something about the severity of what is unfolding.
What About the Yen Carry Trade?
For those readers more practiced in financial markets, the follow-up question is what next for the yen carry trade. It’s dead. For years, investors borrowed cheaply in yen to fund higher-yielding U.S. dollar assets — a trade that anchored global capital flows. Since April 2025, the U.S.-Japan 10-year yield differential has narrowed to its lowest level since 2021, yet the yen has continued to weaken. The two variables that historically moved in lockstep have decoupled.
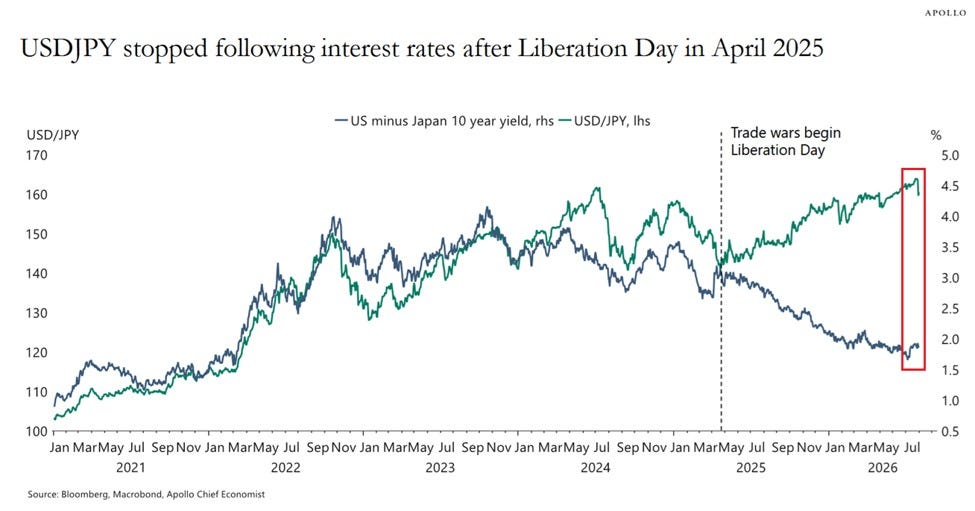
Markets are no longer pricing the yen on interest rate differentials. They are pricing it on Japan’s fiscal reality — one of the highest debt burdens in the world and servicing costs that are becoming impossible to ignore. The carry trade didn’t just unwind. It broke. What replaces it is more troubling: a currency under pressure from a slow-burning loss of confidence.
Earlier in 2026, the New York Fed conducted quiet “rate checks” while Bessent publicly denied any intention to intervene. The message was clear: we are watching, not acting. By late July, watching was no longer sufficient. The yen had deteriorated to the point where the risks — to Japan, to Asian currency stability, and to the U.S. Treasury market — outweighed the optics of abandoning a strong-dollar stance.
The intervention bought time. It always does. But treating the symptom while the underlying disease goes unaddressed is not a strategy. It is a delay. And markets are beginning to price that distinction.
Why Should Canadians Care?
Japan may feel distant, but global risk is synchronized — and Canada is not insulated from what is unfolding. A destabilized yen, a disorderly unwind of carry trades, and rising global bond yields do not stay contained within Japan’s borders. They ripple through capital markets, push up borrowing costs, and tighten financial conditions everywhere — including here.
Canada enters this environment in a weakened state. The last thing Canada needs is an external shock that forces global long-term interest rates even higher.
Secretary Bessent understands the stakes and bought some time last week. But interventions are band-aids, not cures. The underlying fiscal realities in Japan, and the contagion risks they carry, remain very much in play. Canadians would do well to pay attention to what happens next in Tokyo. It will matter in Ottawa whether they do or not.
Now this is a great article.
Don’t worry Carney will figure it out and Bessent is a liar and no friend of Canada.